[01]
General Liability
- Premises and products rated separately
- Occurrence and claims-made forms
- Deductibles from $500 to $100,000
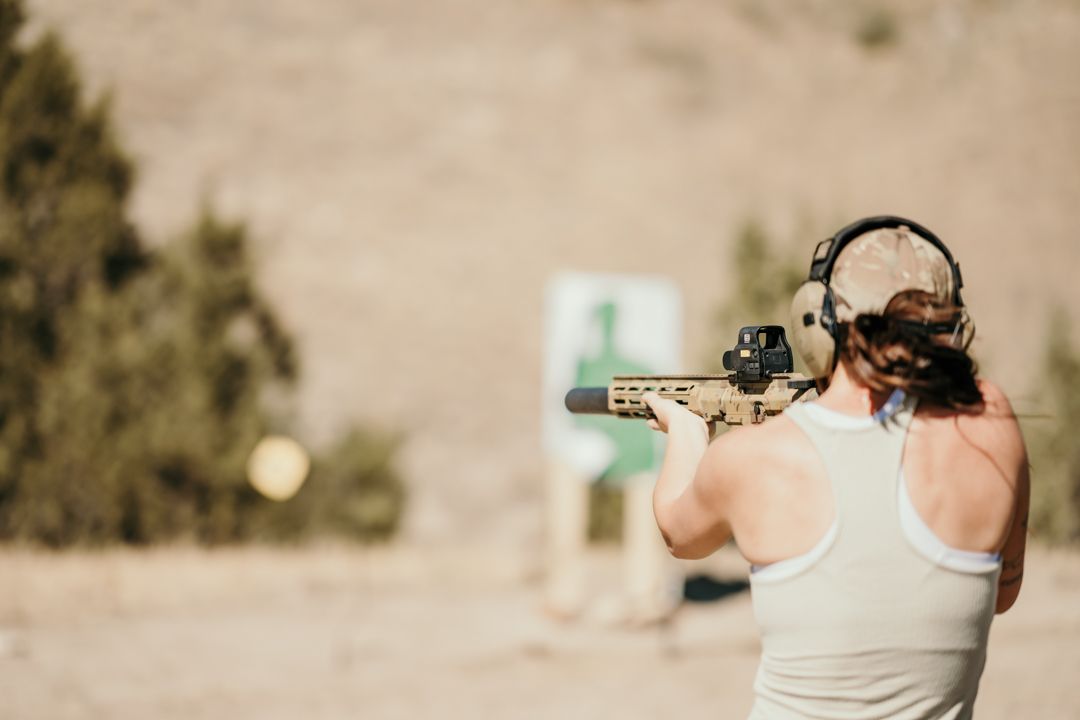
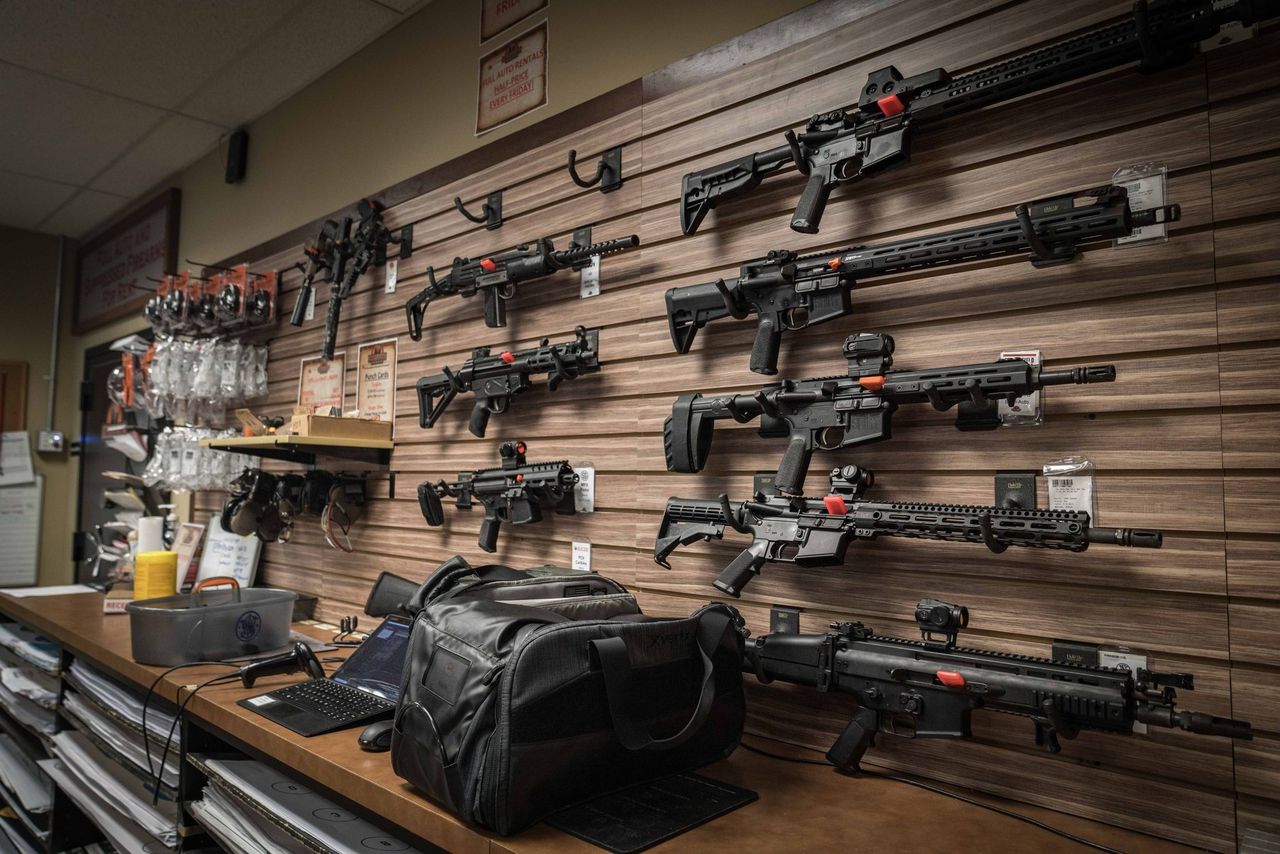
Insurance for the firearms, defense and tactical industries, written by people who shoot. Ranges, FFLs, manufacturers, defense contractors and clubs, rated on the operation you run, not a class code that nearly fits.
Firearms. Defense. Tactical.
Most markets price a gun shop, a range or a defense contractor like any other business. We rate a range per lane, a club per member and a manufacturer on what it builds, and we show you what is driving the price.
More about us[01]
[02]
[03]
[04]
Sectors
Firearms, defense and tactical. Every file we work is one we understand.
Carriers
More than twenty markets that still write this kind of risk, so you are never stuck with one answer.
Excess limits
Excess and umbrella built in layers above your primary policy.
States licensed
Licensed in all fifty. A second location does not mean a second broker.
A call or an email. Lanes, bench, dock, membership, acreage, whatever the operation is. Ten minutes of plain description is worth more than a form you had to guess your way through.
Rated on the details of your operation rather than a generic code, then taken to the carriers who still write this kind of risk. Premises and products separated, and inventory scheduled by category.
What it costs, which carrier, and what moved the price. If something in the operation is driving the price, you hear it from us while there is still time to do something about it.
Before Brent, we were underinsured and paying far too much. With his help, we’re now fully covered, added cyber insurance, and still saved $20K in premium. I can’t recommend him enough.
Roughly: what you run and how big it is. Lanes for a range, members for a club, acres for a preserve, gross receipts for a shop. Your FFL details, who you’re with now, and any loss runs from the last five years. If you don’t have all of it to hand, call anyway.
Because that’s how a range is rated. Price a range on revenue instead of lanes and the premium can come out badly wrong. We ask for the unit your operation is really rated on, which is most of why our numbers look different.
No, we’re a broker. We place your risk with the carriers who still write this kind of risk, and we tell you straight when something is going to be difficult rather than letting you find out at renewal.
Then it needs a person, and that’s usually a good sign rather than a problem. Unusual operations are most of what Brent, our agency principal, spends his time on.
Yes. Non-renewals in this space are almost always the carrier walking away from the class, not a judgment about how you run your shop. That is a market problem, and finding the market that still writes you is the job.
Yes. We’re licensed in all fifty states. A second location or a move across a state line is not a reason to start over with somebody new.